RESTAURANTS · IDAHO FALLS & SOUTH JORDAN · LICENSED IN IDAHO AND UTAH
If you run a restaurant, I'm your guy.
Restaurants are my number one thing — family restaurants, pizzerias, bars and taverns, cafés, everything down to the food trucks — and I carry restaurant programs most agents simply don't have. I'm a business owner myself, so I get what you actually need from an insurance guy: coverage that protects the business and the livelihood behind it, the best price that coverage can be had for, and as little of your time and energy as insurance can take. If you run a restaurant in Idaho or Utah, we should probably talk.
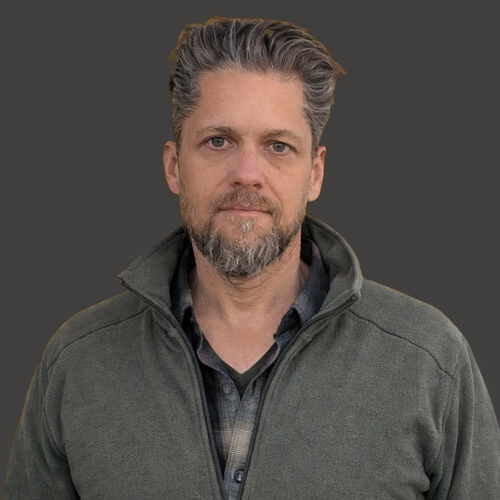
Ben Page
Principal · Idaho Falls & South Jordan
WHY PEOPLE TEXT ME
You don't have time to wait on hold.
THE NUMBER
Up to 40% is a real number.
I carry restaurant programs most agents can't offer — real, A-rated companies; the programs are just hard to get into. Getting you in is my job, and that's exactly why the number is real. Restaurants with a decent record who moved their work comp to me have saved up to 40% — and on the restaurant package (property and liability) too. Not everyone saves that much; it depends on your record and your operation. It starts with one text.
WORK COMP
If your work comp is with the state fund, you probably don't have to be.
How businesses end up there, and how to tell when you can do better →
Four things set your work comp price — and the biggest is the program you're in. Companies don't all charge the same rates, and the best programs take an agent who can reach them. The other three: the payroll you report, the class of work you report it under, and your claims history. Report payroll clean and broken out by class and the audit has nothing to argue with. Report it loose and the auditor makes the assumptions for you, and they don't go your way. And on qualifying setups, pay-as-you-go bills off your real payroll — it links with QuickBooks or most any accounting system — so the audit stops being a surprise — and it cuts the payroll-reporting busywork, which is a savings of its own.
THE AUDIT
The audit is the whole year, settled in one envelope.
Your work comp premium all year is an estimate. The audit is the true-up: real payroll, real job classes, and whatever your records can prove. Restaurants get hurt here more than most, because payroll moves every month and overtime, tips and owner pay all get handled differently. And it isn't only work comp — the restaurant package can get audited too. The prep is your bookkeeper's job — you need one (and here's what I do for them). And if a bill has already landed — it might even be right; not every surprise is a mistake — send it over and I'll tell you straight whether it's worth challenging.
Alcohol claims are excluded from general liability by name — and Idaho and Utah both have laws that let a lawsuit over an overserved customer reach the restaurant. Liquor liability is its own line. If you pour, serve, or even just let people bring their own, it's worth a look — send me your policy and I'll tell you what it actually says.
THE PACKAGE
Nobody has re-read your package since you opened.
No two restaurant packages read the same. They're built from dozens of pieces and they're extremely customizable — which means it's easy to spend too much on coverages you don't need and not enough on the ones you do. The fix is somebody who knows the pieces and walks you through your choices — what doesn't fit, what's missing, what needs updating as the restaurant changes. My job is to help you navigate your choices. A little work up front, a check-in once in a while — not hard with someone who knows what they're doing. Send yours over and I'll tell you what's actually exposed. And if a landlord or a delivery app asks you for a certificate, send me the request and I'll get it back to you.
Everything else, one person.
Commercial auto, and your home and auto too, so it's one person for all of it instead of three different agents. I keep your renewals and paperwork in one place, and I tell you what's coming before it's due, so you're running the restaurant instead of chasing paper. ¿Prefieres español? Escríbeme.
FOUR NOBODY BRINGS UP
Four gaps I find that nobody asks me about.
A restaurant policy is more customizable than most owners ever hear — there are dozens of levers on one. These are just four I keep finding un-pulled.
When your cook takes his own car to the store. Somebody runs out for garnish, drops the deposit at the bank, takes a to-go order across town. If they cause a wreck, your restaurant can get named in that lawsuit right alongside them — and your general liability policy won't answer it, because it excludes anything involving a car by design. What answers it is a line called hired and non-owned auto: coverage for cars your business uses but doesn't own. It's inexpensive, and on most restaurant policies I read, it simply isn't there.
Spoilage and contamination are two different problems. Everybody thinks about spoilage — the walk-in dies overnight and you eat the inventory. That's your property. Contamination runs the other direction: a bad batch, a supplier's problem, somebody gets sick, the health department closes you while they sort it out. That one brings cleanup, lost days and a claim from a customer, and it's usually its own separate line. Most packages I open have one of the two, not both.
The build-out you paid for. If fire takes the space, the landlord's policy is written for the landlord — and your lease probably makes the build-out yours to insure. Tenant improvements coverage is what brings your kitchen, your bar and your dining room back. Most owners carry too little of it, or none.
A lawsuit from someone on your own payroll. Wrongful termination, harassment, discrimination — your general liability policy excludes all of it. Restaurants turn staff over faster than almost any business in the country, and every hire and every firing is one more chance at a claim. Employment practices liability is the policy that answers it. I've been on the wrong end of this one myself.
And that's before the small print: the sign out front usually has to be named on the policy, glass can be its own line, and no two policies read the same — even from the same company. That's why I read yours.
Send me your dec page and I'll tell you which of the four you have →
THE COVERAGES, IN PLAIN ENGLISH
What each policy actually does.
- The restaurant packageProperty and liability in one policy — the space, the kitchen and equipment, the food in the walk-in, and the customer-slips-and-falls side. The most customizable thing you own.
- Work compYour people, when they get hurt. Priced off payroll, trued up at the audit — in a kitchen, the big line with the most room to move.
- Commercial autoCatering runs, deliveries, a van the business owns — personal auto policies back away from work use.
- Liquor liabilityIf you serve alcohol, the regular liability side wasn't built for what happens after over-serving — this is the piece that is.
- UmbrellaSits on top of your other liability limits and picks up where they stop.
- Home & auto tooI write the owner's personal side as well, so it's one person for all of it. Why that matters more for owners →
The restaurant insurance mistakes I keep seeing →
Plain English on any of these is one text away. ¿Prefieres español? Escríbeme.
BEN'S TAKE
A job applicant I never hired sued my first business — I'd bought every coverage my agent offered, and the one I needed wasn't in the stack. That's why I do this.
How I think about coverage
Cover the big stuff first — insurance is not a carton of eggs. Raise the deductible on what you can absorb, and put the difference toward the claim that could close the doors.
A note from a longtime client.
Ben's not just our agent — he's part of our team. I manage the books for Pizza Pie Cafe and have worked with Ben for over a decade. He stays involved, keeps things organized, and helps us address issues before they turn into problems.
Mandi Tomlinson · Bookkeeper, Pizza Pie Cafe
RESTAURANTS I WRITE
If you run one of these, I write it.
- Pizza & quick-service
- Full-service & family
- Bars & taverns
- Cafés & diners
- Sports bars
- Breweries & brewpubs
- Fine dining
- Multi-location
- Tacos & food trucks
Rather not text? Type it here instead — you can attach a photo of your dec page or audit bill.
A sentence is plenty. It goes to me.
START HERE
Text me what you've got.
A photo of your dec page or your audit bill is enough to start. It costs nothing and commits you to nothing. If I'm not your guy, I'll tell you — and point you to someone who is.