Most business owners have insurance.
Few have a guy who understands insurance
and running a business.
I'm Ben Page. Our family of agencies serves thousands across Idaho and Utah — I personally serve my own clientele of about 150 business owners, mostly restaurants and contractors. I'm a business owner myself, so I get how much of a pain insurance can be, and my goal is to make it as easy as possible. You get my direct number, not a queue. Hablo español.
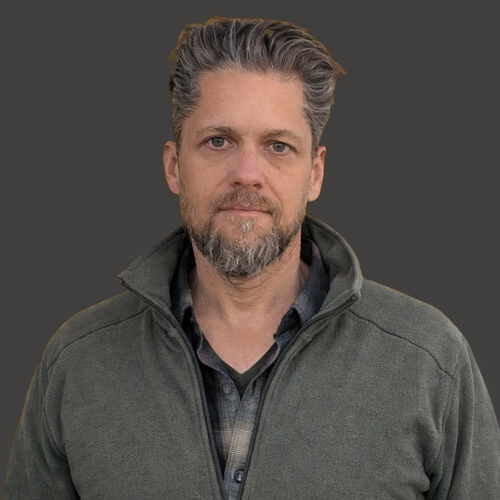
Ben Page
Principal · Idaho Falls & South Jordan
THE NUMBER
Up to 40% is a real number.
I carry programs most agents can't offer — real, A-rated companies; the programs are just hard to get into. Getting you in is my job, and that's exactly why the number is real. Owners with a decent record who moved to me have saved up to 40% — on work comp, and on the main package policy (property and liability) too. Not everyone saves that much. My job is stretching your dollar: coverage that fits your risk tolerance and your circumstances, and I help you navigate those choices.
Most people move work comp first, out of the state fund — then end up moving everything else over. It starts with one text.
WHY I DO THIS
It started when a job applicant sued me.
I founded my first business near Boise — a financial services company. A job applicant I never hired sued me. I'd bought every coverage my agent offered; the one I needed wasn't in the stack. It took two years. I had to find my own defense attorney, pay for it all myself, and keep running my business while the suit put me through hell.
That's why I do this. I'm passionate about small business owners, and I understand — personally — what the right coverage is worth.
Insurance companies keep a reputation file on your business — payment history, lapses, whether the audits got done. They don't advertise it, and most agents never bring it up. I can tell you what they look at and help you build a plan — not just to save money now, but so the price keeps moving your way year after year.
HOW IT USUALLY GOES
Almost nobody moves everything at once.
Here's the pattern with most of my clients:
- Work comp first. Usually out of the state fund and into one of my programs — that's where the savings tend to start.
- Then the package. The property and liability policy that carries the business.
- The rest of the business. Commercial auto, equipment, whatever your operation runs on.
- The personal side. Home, auto, the cabin, the Airbnb — I write those too, so the business and personal sides actually line up.
- Term life. The long-range piece — the coverage that protects the family behind the business if something happens to you.
- One place for all of it. Everything organized and kept that way — one person, one number to call.
A big slice of what you pay for work comp comes down to which class codes your payroll is filed under. Most owners have never seen theirs, and a wrong one can ride quietly for years. Sometimes payroll can legitimately be split across more than one code — that alone can save real money. Send me your declarations page — I'll read it and tell you what it says.
ABOUT THE AGENCY
The agency my dad founded. The desk I keep small.
Page Insurance is my family's agency — my dad started it in 1998. Independent means I shop your account across companies instead of where a quota points. I've got a real team behind me for quoting, certificates and paperwork, and I write the owner's home and auto too, because the gaps that hurt usually sit between policies, not inside them. But you deal with me. That's the point.
HOW IT STARTS
What the first text actually looks like.
No phone tree. No quote bot. No "an agent will reach out in 3–5 business days." You text the person who actually knows your account — me.
Hi Ben — just emailed you my current insurance papers. 12 years in business, never had a claim. Mind taking a look?
Hi Matt, good to connect. Give me a few minutes to go through them.
👍
Good news — I had enough in your email to build a full quote. Here's your proposal, and it shows you the two gaps I found in what you have now: benpageins.com/matt
Just looked at it — that's awesome. Thank you!
Call me and we'll walk through it together.
RESTAURANTS AND CONTRACTORS
Restaurants and contractors. That’s most of my clientele.
Restaurants
A lot of restaurants are stuck in the state fund because it made sense when they opened — and likely doesn't now if you've got a good record. I have restaurant programs most agents can't access. And restaurant policies aren't created equal: there's real room to fit one to your operation, so you're not paying for things you don't need.
Contractors
A certificate the GC wants today, subs whose payroll lands on your audit because the certificate never showed up, the installation floater nobody mentions, and an experience mod that a new company name doesn't erase.
Everyone else
About a dozen other industries, too. Not ready to gather quotes? Call me — a couple of minutes on the phone and I can usually give you an idea of what's possible, so you can decide whether a full quote is worth your time.
WHAT MOST AGENTS WON'T SAY
What most agents won't tell you.
Any agent can make it cheap. Strip the coverage, hit whatever number you wanted to hear — and then the audit comes and doubles the bill. Cheap isn't a strategy.
Your agent should do more than set it and disappear. A review every year, so you can decide whether the coverage still fits the business. Your policies read side by side, so you can see where one ends and the next begins. Your bookkeeper brought in before the audit instead of after the bill. That's the actual job, and it's the part nobody quotes you on.
Then
Set the policy, disappear until renewal, hope nothing changed.
Now
Review it yearly — and any time something changes. Keep your whole insurance picture organized in one place. Tell you straight what’s worth changing and what’s fine as it is.
ONE PLACE FOR ALL YOUR INSURANCE
The full lineup.
If you spot something in here you've been missing, that's the point.
The business side
- Work compPay-as-you-go tied to your real payroll — no big up-front deposit on qualifying setups. Bundles with the package. State-fund alternatives most agents can't reach.
- The package policyProperty, general liability, and the extras your industry actually needs — liquor liability, spoilage, whatever fits the operation.
- Commercial autoTrucks, trailers, employees driving — the gaps personal auto policies leave open.
- Everything else on the businessUmbrella, tools and equipment, installation floaters, employment claims — the coverage I didn't have when my own business got sued. There are a lot of ways for a policy set to go wrong; the fix is someone who knows what they're doing.
The personal side
- Home & autoWritten alongside the business, so the discounts stack and the gaps don't.
- The second placesThe cabin, the landlord place, the Airbnb — each one covered for what it actually is.
- The toysBoats, side-by-sides, snowmobiles, motorcycles — the stuff weekends are made of.
- Term lifeThe long-range piece that protects the family behind the business.
Start a term life policy with the right company and your other policies often earn a discount. On the right-sized account, that discount can run close to the term premium itself — with some smart shuffling, real coverage for your family at little or no added cost. I'll show you the math either way.
The point of all of it: personalized coverage, a holistic plan — and one person to call about any of it.
Notes from longtime clients.
Ben's not just our agent — he's part of our team. I manage the books for Pizza Pie Cafe and have worked with Ben for over a decade. He stays involved, keeps things organized, and helps us address issues before they turn into problems.
Mandi Tomlinson · Bookkeeper, Pizza Pie Cafe
Ben is always ready to help me with whatever I need. All my business goes to Ben — he's reliable and honest.
Greg Howe · Owner, Howe Deep LLC · General contracting
I own and run several businesses, and Ben has all of it — the companies, the house, the cars, the toys. I've got the best insurance agent in the world.
Dustin Harris · Serial entrepreneur
As a business owner and financial planner, I value relationships built on trust. That's why I've worked with Ben for so long.
Matt Johnson · Business owner & financial planner
BEFORE WE START
I'm your guy if — and I'm not your guy if.
And if I'm not the right fit, I'll tell you, and point you to someone who is.
How I think about coverage
Cover the big stuff first — insurance is not a carton of eggs. Raise the deductible on what you can absorb, and put the difference toward the claim that could close the doors.
I'm your guy if
- You'd rather hear the truth than the pitch.
- You want one person for the business and the personal side.
- You keep good books and pay on time.
- Coverage right first, then the best price for it. In that order.
I'm not your guy if
- You want the cheapest Swiss-cheese policy, whatever it covers.
- You want an agent you never hear from.
- Late pays, skipped audits, no bookkeeper — that history ties my hands.
THE GUIDES
The six things owners ask me about most.
Free. No email required.
Rather not text? Type it here instead — you can attach a photo of your dec page or audit bill.
A sentence is plenty — or just attach a photo of your dec page or audit bill and I'll tell you what it says. It goes to me.
START HERE
Start it with a text. Or type it here.
Tell me what you run and what's worrying you — or just text a photo of your dec page and I'll tell you what it says. It costs nothing and commits you to nothing — worst case, you walk away understanding what you already have, with ideas to make it better. If I'm not your guy, I'll tell you — and point you to someone who is.